Land ownership documents
Organise the title, sale deed and other land records a lender may request before assessing construction finance.
Learn moreSelf-construction guidance in Bangalore
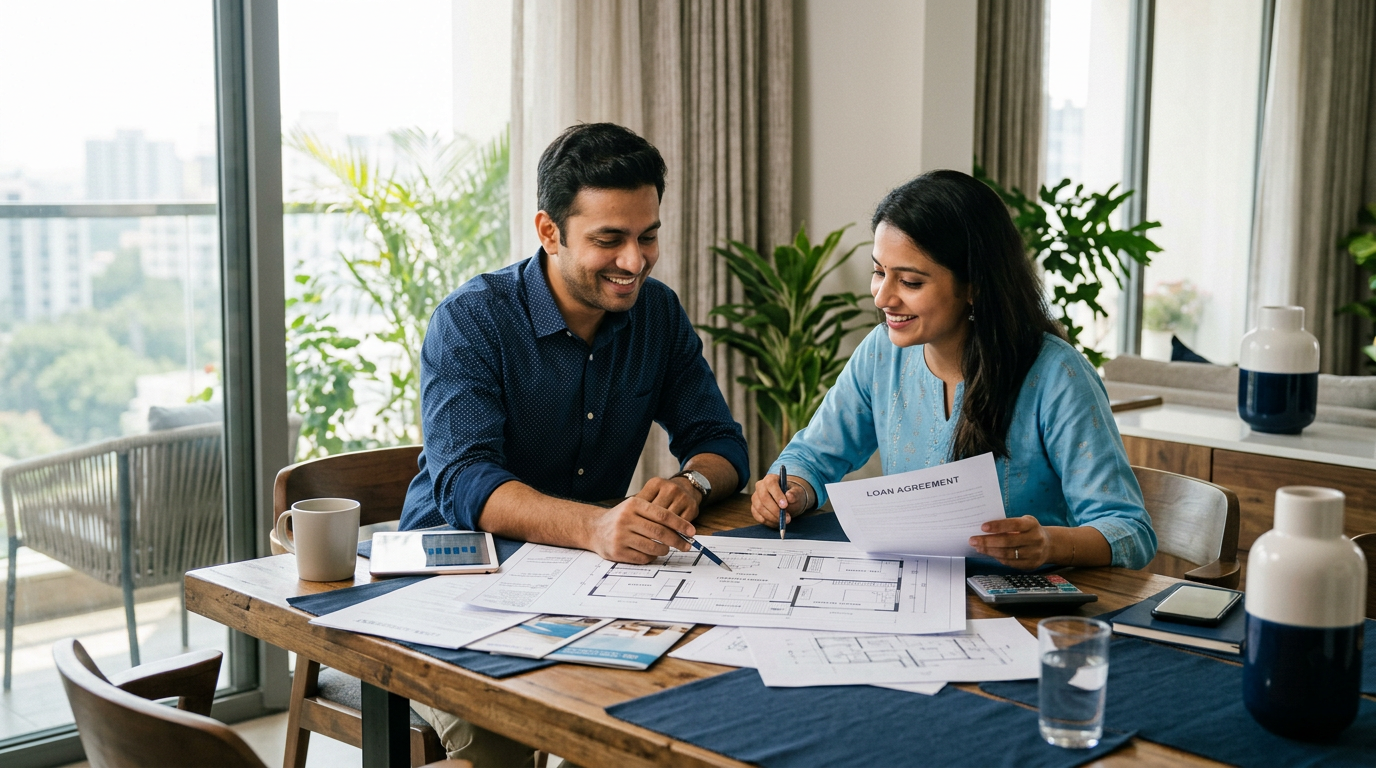
A home construction loan is considered for borrowers building on land they already own. ZenMarg helps you prepare the ownership papers, approved plan, cost estimate and construction sequence for a clearer lender conversation. The lender decides eligibility, valuation, sanction, inspections and disbursement conditions.
Free for borrowers
ZenMarg is paid by the lender, so you pay us nothing.
One place to start
A home loan is not only an eligibility calculation. It is a sequence of conversations, documents, property checks and decisions. ZenMarg helps you see what comes next without pretending to replace the lender.
Organise the title, sale deed and other land records a lender may request before assessing construction finance.
Learn morePrepare the sanctioned building plan, permissions and a realistic cost estimate for the proposed construction.
Learn moreUnderstand how construction progress may connect to inspections, conditions and later disbursement requests.
Learn moreCompare questions about plot value, construction cost, borrower income and the lender’s technical process.
Learn moreKeep visibility on site visits, progress certificates, invoices and other evidence requested during construction.
Learn moreAsk how disbursed amounts, pre-EMI or full EMI treatment and the final repayment schedule may work.
Learn moreDifferent starting points
The right preparation depends on your income pattern, property type, stage of purchase and existing commitments.
Before you apply
You do not need every answer before your first conversation. Starting with the right questions helps keep the process grounded.
Clear roles
Good guidance is transparent about where support ends and the lender’s responsibility begins.
Prepare with context
Requirements vary by lender and local authority. These are the practical areas to prepare before requesting a construction-loan assessment.
The lender may review ownership, encumbrance and other title records for the plot. Exact documents and legal standards vary by lender.
An approved plan, applicable permissions and evidence that the proposed construction is permitted can be important to the assessment.
A structured estimate from the relevant professional can help the lender understand the proposed construction cost and funding requirement.
Later disbursements may depend on inspections, progress evidence and lender conditions. Stage definitions are lender-specific.
Income, credit history, existing EMIs and the proposed construction budget shape the affordability discussion.
What varies by lender
Construction-loan eligibility, permitted plot types, plan requirements, inspection rules, disbursement stages, pre-EMI treatment, fees and documentation vary by lender. Confirm the current policy before relying on an illustration.
A practical sequence
Collect ownership, title and encumbrance records and identify any legal or authority questions before planning finance.
Keep the approved plan, permissions, professional estimate and proposed construction schedule together.
Ask about valuation, technical inspection, sanction conditions, own contribution and the evidence needed for each stage.
Maintain progress records and confirm each inspection and release condition before starting the next stage.
Fees and transparency
[PLACEHOLDER: confirm how ZenMarg is paid before launch. Do not publish a specific fee model until this is confirmed.]
Keep your information safe
Please do not send PAN, Aadhaar, bank statements or property documents through the website form. We will explain the appropriate next step first.
A lender may consider construction finance when you own a suitable residential plot and meet its legal, technical, income and credit requirements. The lender decides whether the plot and proposal qualify.
Lenders commonly ask for an approved building plan and applicable permissions, along with a construction estimate. The exact authority documents vary by location and lender.
The lender may release funds in stages linked to construction progress after inspections or evidence. The number of stages, progress thresholds and documents are lender-specific.
It may. Technical inspections or progress verification can be part of the lender’s process before later disbursements. Confirm the inspection schedule and cost, if any, in advance.
Treatment depends on the lender, the amount disbursed, the product terms and the repayment schedule. Ask for the written illustration showing when interest and principal repayment begin.
They can, but additional funding is not automatic. Discuss contingencies, own contribution and any revised assessment with the lender before relying on extra borrowing.
Continue exploring
Prepare income, obligation and property information for a broader affordability conversation.
ExploreSee how application checks, conditions and disbursement fit together.
ExploreGet practical support preparing questions for a lender-led construction assessment.
ExploreYour next step
Share only the basics. We will contact you to understand your situation before any document discussion.