Initial enquiry and eligibility
Clarify your purchase plan, income pattern, commitments and broad borrowing range before approaching a lender.
Learn moreHome loan process in Bangalore
Every home loan moves through a sequence of conversations, checks and decisions. This guide explains the stages, who does what and where a well-prepared application can still face questions.
Free for borrowers
ZenMarg is paid by the lender, so you pay us nothing.
One place to start
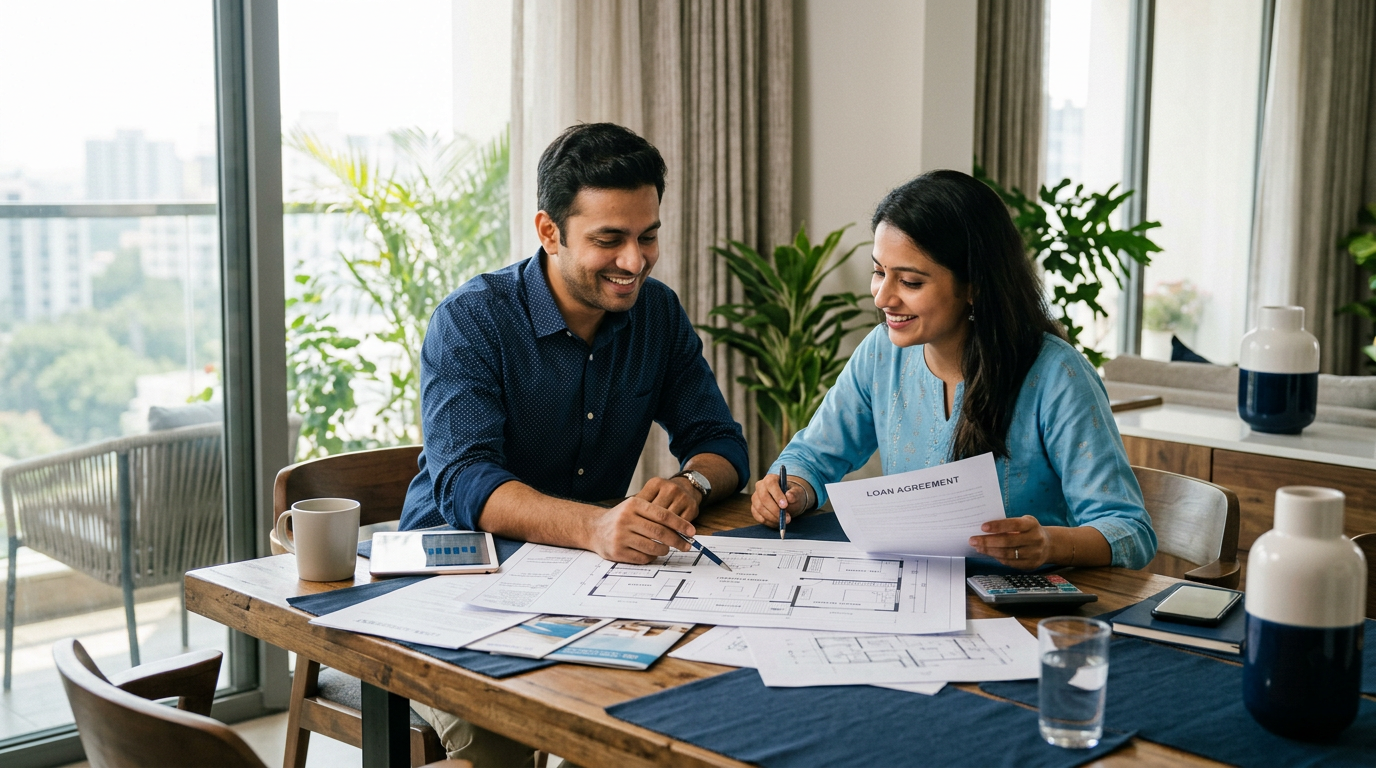
A home loan is not only an eligibility calculation. It is a sequence of conversations, documents, property checks and decisions. ZenMarg helps you see what comes next without pretending to replace the lender.
Clarify your purchase plan, income pattern, commitments and broad borrowing range before approaching a lender.
Learn moreCompare lender fit, policy, pricing, service expectations and property acceptance questions.
Learn morePrepare the information and documents needed for a complete application submission.
Learn moreUnderstand how lender underwriting and credit bureau checks fit into the decision.
Learn moreRead the sanction letter carefully, including its validity, conditions and approved amount.
Learn moreTrack title verification, approvals, valuation and property-level requirements.
Learn morePrepare for signing, own contribution and full or part disbursement.
Learn moreKeep questions, updates and lender conditions organised through the final stage.
Learn moreDifferent starting points
The right preparation depends on your income pattern, property type, stage of purchase and existing commitments.
Before you apply
You do not need every answer before your first conversation. Starting with the right questions helps keep the process grounded.
Clear roles
Good guidance is transparent about where support ends and the lender’s responsibility begins.
Prepare with context
The sequence below is a practical framework. The exact order, documentation and review depth can vary by lender, applicant profile, property type and construction stage.
You provide accurate information and approvals. ZenMarg helps you prepare and coordinate. The lender assesses the application and makes the lending decision.
A strong income profile does not remove the need for title, approval, construction and valuation checks on the property.
Timelines depend on the lender, property, document quality, applicant responsiveness and whether additional checks are requested.
Keep copies of applications, sanction conditions, lender communications, legal observations, valuation questions and your own contribution plan.
What varies by lender
No fixed timeline should be assumed. Lenders follow different internal processes, and a property with missing approvals or an unresolved title question may require additional review.
A practical sequence
You share your goal, employment type, income context, existing obligations and property stage. ZenMarg helps organise the conversation and identify broad eligibility questions. A change in income, incomplete information or unresolved credit history can slow the next step.
You and ZenMarg discuss lender options that may suit your profile and property. The lender’s policy, acceptable property types, pricing, service model and document requirements matter beyond a headline rate. A poor fit or changing requirements can lead to rework.
You provide the relevant information to the lender through its approved process. ZenMarg can help you understand a checklist and sequence the preparation. Missing pages, inconsistent figures, outdated records or unclear business income commonly create follow-up.
The lender reviews income, obligations, repayment history and the credit bureau report, along with the application details. You may be asked to clarify enquiries, settlements or discrepancies. Multiple applications, unexplained liabilities or mismatched information can require additional assessment.
A sanction letter records the lender’s decision in principle or approved terms, subject to its stated conditions. Read the amount, interest structure, fees, validity or expiry, required documents and pre-disbursement conditions carefully. A sanction is not the same as disbursement and can lapse or change if conditions are not met.
The lender’s legal team reviews title documents, ownership history, encumbrances, approvals and other property papers. For a resale or builder purchase, the review may involve several parties. Missing chain documents, title gaps, approval questions or disputes can pause the file.
A technical evaluator may inspect the property, construction status, layout, location and value for lending purposes. The lender may base financing on its accepted valuation rather than only the agreed purchase price. A lower valuation, deviation or incomplete construction can change the funding position.
After conditions are satisfied, agreements are signed and the lender confirms the disbursement requirements. A completed property may involve full disbursement, while an under-construction property may receive part disbursements linked to construction milestones. Your own contribution, registration or builder documents and lender conditions must be aligned before release.
Fees and transparency
ZenMarg is paid by lenders and does not charge borrowers.
Keep your information safe
Please do not send PAN, Aadhaar, bank statements or property documents through the website form. We will explain the appropriate next step first.
There is no single reliable timeline. It depends on the lender, your document readiness, credit assessment, property title, valuation, construction stage and how quickly questions are resolved.
No. A sanction letter sets out approved terms and conditions, but disbursement normally follows completion of legal, technical, documentation and contribution requirements. Read its validity and conditions carefully.
Common causes include incomplete documents, property title or approval issues, valuation below the agreed price, changes in employment or income and discrepancies in a credit report or application details.
Part disbursement means the lender releases funds in stages, often linked to construction progress and lender verification. The exact schedule and conditions are decided by the lender and may also depend on builder documentation.
ZenMarg can help reduce avoidable confusion by improving preparation, tracking questions and coordinating communication. The lender controls credit, legal and technical assessment, so no intermediary can promise a decision or fixed timeline.
Continue exploring
Explore eligibility, lender options, documentation and property-check support.
ExploreUnderstand the income, obligations and property factors lenders consider.
ExploreTalk through your situation before sharing sensitive documents.
ExploreYour next step
Share only the basics. We will contact you to understand your situation before any document discussion.